Skip to content
Financial Operations & Bilingual Support
Financial Services BPO: A Practical Guide to Scope, Controls, and Cost
Evaluate outsourced financial support through defined authority, security, comparable costs, measurable service, and a controlled bilingual nearshore pilot.
TL;DR — Quick Takeaways
- Separate administrative support from credit, claims, compliance, and other decisions requiring specific authority.
- Document permissions, oversight, data handling, exceptions, and incident escalation before launch.
- Compare equivalent capacity and total costs; savings and ROI require different calculations.
- Define resolution and control metrics instead of judging a provider by price or activity alone.
- Pilot one workflow and expand after readiness, quality, and oversight requirements are met.
A growing queue of account questions, incomplete applications, and claim-status requests can pull experienced financial-services employees away from work that needs their judgment. Financial services BPO gives institutions a way to delegate defined operational tasks while maintaining oversight of the customer experience, data access, and decisions made on their behalf.
The business case depends on scope. A partner may handle bilingual support, document indexing, approved payment reminders, or application completeness checks. That does not automatically authorize the team to approve credit, decide a claim, investigate suspicious activity, or provide financial advice. Define the work, permissions, and escalation boundaries before comparing rates.
What Financial Services BPO Includes
Financial services business process outsourcing assigns agreed workflows to an external provider under documented service standards and controls. The provider supplies operational capacity; your organization defines the approved process, monitors performance, and retains the responsibilities that apply to its business.
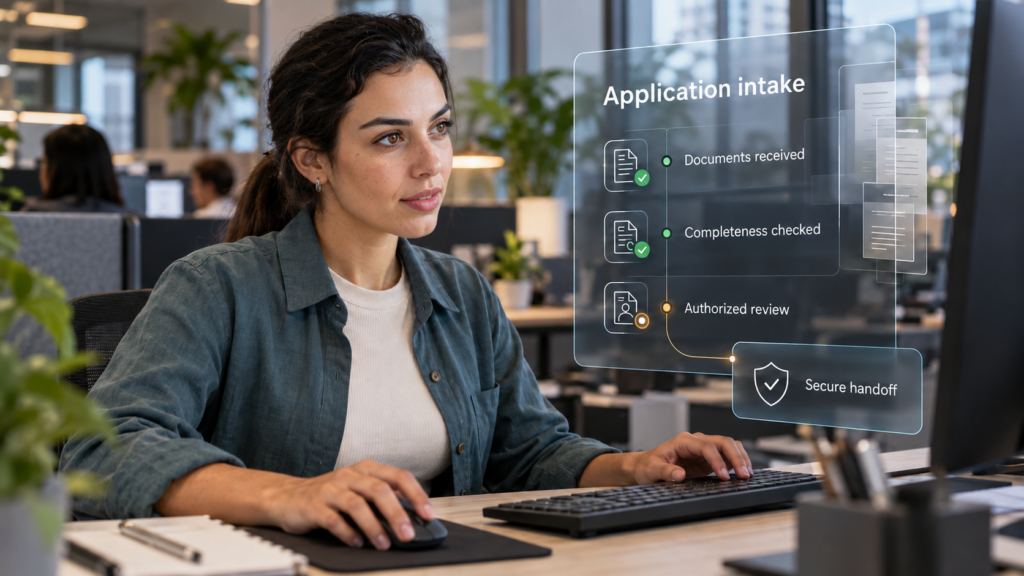
Separate administrative work from decision authority
Application intake and application approval are different services. An agent can check whether required documents are present without deciding whether a borrower qualifies. A support representative can relay an approved claim status without assessing coverage or negotiating a settlement.
Some activities may be delegated to appropriately authorized specialists, depending on the service and applicable requirements. A general contact-center agreement should never be treated as evidence of that authority. Record who may view information, update records, recommend an action, approve it, and communicate the result.
Choose a defined problem to solve
Consider a hypothetical regional lender evaluating after-hours account inquiries. A practical pilot could cover identity verification, approved balance and payment information, and urgent escalation. Credit decisions and account exceptions would follow separate authorization paths. This gives the team a measurable service scope rather than an open-ended instruction to handle everything.
Core Financial Services BPO Workflows
The best starting point is usually repeatable work with clear procedures and a dependable source of information. Compare the workflow, required permissions, customer impact, and review requirements before handing it over.
| Service area | Potential support scope | Boundary to document |
|---|---|---|
| Account and card support | Verified account inquiries, payment questions, approved card-service requests | Verification, permitted actions, fraud escalation, and access limits |
| Payment follow-up | Approved reminders, account updates, and permitted payment arrangements | Contact rules, disputes, opt-outs, script approval, and arrangement authority |
| Back-office processing | Document indexing, data entry, application completeness checks | Required fields, validation, audit history, and approval ownership |
| Identity-review support | Document collection, checklist review, and routing of mismatches | Institution-approved procedures and escalation to authorized compliance staff |
| Claims administration | Intake, missing-information requests, and approved status updates | Activities requiring licensing, coverage decisions, and settlement authority |
| Lead qualification | Interest checks, intake questions, scheduling, and handoff notes | Approved criteria, permitted outreach, and boundaries on advice or commitments |
Customer support and payment questions
Routine account contacts can still be sensitive. Agents need reliable identity-verification procedures, current information, and clear limits on what they may disclose or change. An answer should come from an approved system or knowledge source, not from memory or an improvised explanation.
Document processing and identity-review support
Document queues can grow quickly during onboarding or a product launch. A provider may collect files, identify missing information, and route mismatches under your procedures. Confirm the exact KYC or AML support scope, required expertise, and approval responsibilities rather than assuming document review is equivalent to a complete compliance function.
Our guide to accounting and finance outsourcing provides related context for evaluating administrative finance workflows. Confirm any specialized service separately in the proposal.
Claims, collections, and qualified handoffs
Claims intake should preserve the customer’s account of the issue and distinguish administrative updates from decisions requiring authorized personnel. Payment follow-up needs approved treatment of disputes, contact preferences, and sensitive circumstances. Lead qualification should prepare a useful conversation without promising approval, rates, or coverage outside the agent’s authority.
Bundling related administrative tasks may reduce transfers, but a single team should not receive broader access merely for convenience. Match each role’s permissions to the work and preserve separation between preparation and approval where required.
Build Oversight and Security Into the Operating Model
Outsourcing creates a third-party relationship that needs active management. The interagency guidance on third-party risk management describes a risk-based approach across the relationship life cycle for banking organizations supervised by the issuing agencies. It is a useful reference for planning, due diligence, contracts, monitoring, and termination; confirm the requirements applicable to your own entity and services.
Request evidence for the controls that matter
- Access: Named accounts, appropriate authentication, role-based permissions, periodic review, and prompt removal when roles change.
- Data handling: Approved storage, restrictions on local downloads, retention rules, secure transfer, and controlled exports.
- Quality monitoring: Documented scorecards, calibrated reviews, and appropriate recording, consent, access, and retention practices.
- Record protection: Minimized sensitive information in notes, suitable masking or redaction, and controlled access to original documents.
- Workforce preparation: Role-appropriate screening, training, supervised practice, and documented access approval.
- Traceability: Relevant access and change logs, monitoring responsibilities, and a clear incident-escalation process.
- Continuity: Tested recovery procedures, approved fallback workflows, and defined restoration priorities.
The FTC Safeguards Rule applies to financial institutions under FTC jurisdiction and includes responsibilities concerning service-provider protection of customer information. It should not be described as the rule for every bank, insurer, or financial-services company. Identify the applicable regulator, data obligations, and contractual controls with your compliance team.
Give urgent exceptions an actionable route
If a caller reports an unauthorized transfer, the agent should follow the client’s approved verification and urgent fraud-escalation procedure. Blocking an account or attempting to stop a transaction requires explicit system permissions and authority. Never promise that a transfer can be frozen or reversed simply because the customer reached the support team.
Build these boundaries into agent training and coaching. Practice unclear requests, failed verification, disputed information, missing documents, and system outages before agents take ownership of the queue.
Evaluate Benefits With a Comparable Cost Model
A BPO program may add coverage, support English-Spanish conversations, clear administrative backlogs, or give internal specialists more time for complex cases. Those benefits depend on hiring, training, system readiness, and management discipline. Extended hours, rapid ramp-up, and continuity should be specified and tested rather than assumed.
Distinguish savings from ROI
Hypothetical first-year comparison: An internal option includes $32,000 in recruiting and initial training, $208,000 in annual salary and benefits, and $18,000 in overtime, totaling $258,000. Suppose a comparable outsourced option includes a $165,000 vendor fee plus $20,000 for transition, retained oversight, and technology, totaling $185,000.
The modeled first-year cost difference is $73,000, or approximately 28.3% of the internal baseline. These figures illustrate a calculation; they are not a CallZent quote, customer result, or savings guarantee. They also do not establish a complete ROI calculation.
Compare the same coverage, workload, productive capacity, quality standards, and service scope. Separate one-time transition costs from recurring costs, and revisit the comparison in later years. Dedicated-team and hourly agreements can include paid available time; outsourcing does not automatically mean paying only for completed work.
Track benefits outside the invoice
Measure whether backlogs age less, applications move through administrative steps accurately, and customers need fewer follow-ups. Do not count faster approval or retention gains as vendor-created value unless the evidence supports that attribution. A smaller invoice can still be a poor result if errors, complaints, or internal correction work increase.
Compare Pricing Models and Performance Together
Different BPO pricing models allocate capacity and volume risk differently. None guarantees quality on its own. Define the billable unit, included supervision, training, technology, minimums, and treatment of rework before comparing rates.
| Model | Payment basis | What to clarify |
|---|---|---|
| Hourly | Agreed billable hours | Scheduled versus productive hours, absence, training, overtime, and supervision |
| Per transaction | Defined completed tasks | Completion criteria, rejected work, exceptions, duplicate submissions, and rework |
| Per contact | Eligible customer interactions | Transfers, repeat contacts, callbacks, minimums, and attribution |
| Dedicated capacity | Agreed team or FTE capacity | Coverage, shrinkage, staffing changes, management, and minimum commitments |
| Outcome or blended | Base fee and/or verified outcomes | Attribution, quality gates, exclusions, incentives, and customer-treatment safeguards |
Do not derive total resolution cost from FCR alone
Dividing a per-contact price by a first-contact resolution percentage does not establish the total cost of resolving an issue. It omits what happens to unresolved issues, how many additional contacts occur, and what internal specialists or other channels contribute.
For a practical measure, divide the relevant costs for a defined issue cohort by the number of those issues resolved under the agreed rules. Include repeat handling and retained-team work within scope, allow enough time for outcomes to mature, and disclose unresolved cases. Compare similar issue types before concluding that one provider is more efficient.
Use measures with clear definitions
- First-contact resolution: Define eligible issues, resolution criteria, repeat-contact matching, and the observation window.
- Average handle time: State included components and compare it with accuracy, issue complexity, and customer outcomes.
- Quality results: Disclose review coverage, critical failures, sampling, and calibration.
- Schedule adherence: Compare actual activity with the approved schedule; it is not simply time logged in.
- Abandonment: Define offered calls, exclusions, callbacks, and reporting intervals.
- Control exceptions: Specify the eligible population, severity, detected failures, and corrective-action ownership.
- Cost per resolved issue: Keep the cost scope, issue cohort, time window, and unresolved population visible.
Outcome incentives should include customer-treatment and control requirements. Rewarding right-party contacts or collections alone can encourage behavior that conflicts with the approved process. Service credits may address specified performance failures, but they do not replace investigation, remediation, or required escalation.
Choose and Launch a Bilingual Nearshore Program
A Tijuana-based team can offer overlapping working hours and English-Spanish support for North American operations. These nearshore outsourcing advantages can simplify live coaching and escalation discussions, but location does not establish expertise, security, or service quality.
Ask for operating evidence
Review relevant experience, staffing plans, representative reports, training materials, quality scorecards, and recovery-test results. If a certification or assurance report is offered, verify the entity, scope, dates, findings, and relevance to your program. Do not treat a logo as proof that every workflow meets your requirements.
Confirm subcontracting, data locations, client access, incident notifications, permitted system actions, and exit support. Evaluate communication through realistic English and Spanish service scenarios, focusing on intelligibility, accuracy, and customer understanding.
Start with a controlled pilot
- Map the work: Document volumes, data, systems, authority, exceptions, and handoffs.
- Complete readiness reviews: Resolve access, contractual, security, compliance, and training requirements before live handling.
- Set a baseline: Agree on quality, customer, coverage, and cost definitions.
- Test and supervise: Use approved practice cases and a limited live scope, with named escalation owners.
- Review before expanding: Assess results, open issues, complaints, and control failures against documented acceptance criteria.
Launch timing depends on the actual workflow and readiness gates. A narrow administrative queue may be simpler than a program involving sensitive permissions or specialized licensing. Avoid committing to a universal launch timeline before those requirements are understood.
Plan for interruption and exit
Cross-training can reduce exposure to absence, but it does not eliminate turnover. Failover can improve resilience, but it must be tested. A second provider introduces its own access and oversight requirements. Agree on permitted fallback work, escalation, recovery, and transfer of records before an interruption occurs.
The right financial services BPO program gives your organization usable capacity, transparent performance, and clear accountability. Start with one well-defined workflow and expand when the evidence shows that both customer service and controls are working.
Frequently Asked Questions
What is financial services BPO?
Financial services BPO delegates defined operational workflows to an external provider under agreed service standards and controls. Scope may include account support, document processing, claims intake, and approved payment follow-up, with documented authority and oversight.
Which financial-services tasks can be outsourced?
Potential tasks include verified account inquiries, document indexing, application completeness checks, administrative claims updates, and permitted lead qualification. Confirm required expertise, permissions, licensing, and review before assigning any workflow.
Does outsourcing transfer regulatory responsibility to the provider?
Outsourcing does not remove the institution’s applicable responsibilities for oversight and third-party risk management. The provider has its own contractual and potentially legal duties. Define each party’s responsibilities and confirm the requirements relevant to the institution and service.
Can a BPO provider support KYC or AML workflows?
A qualified provider may support specified activities such as document collection, checklist review, and escalation. Confirm program requirements, training, data access, and approval ownership. General document processing should not be presented as a complete KYC or AML compliance service.
What security evidence should buyers request?
Review access management, authentication, data storage and transfer, retention, monitoring, incident response, and recovery testing. Validate the scope and currency of any certification or assurance report and compare its findings with the actual workflow and systems.
How is financial services BPO priced?
Models can include billable hours, completed transactions, eligible contacts, dedicated capacity, and outcome or blended fees. Clarify minimums, supervision, training, technology, rework, and exceptions before comparing proposals.
How should an institution estimate outsourcing savings?
Compare equivalent scope, coverage, workload, capacity, and quality. Include transition, retained oversight, systems, and correction costs. Separate first-year and recurring expenses. A cost difference is not, by itself, a complete ROI calculation or a guaranteed result.
Which KPIs should a financial services BPO program track?
Track defined resolution, handling time, quality, adherence, abandonment, control exceptions, complaints, and cost per resolved issue. Disclose review coverage and unresolved cases, and interpret speed alongside accuracy, issue complexity, and customer treatment.
Why consider bilingual nearshore support in Mexico?
English-Spanish capability and overlapping working hours can support customer understanding, coaching, and operational coordination. Verify the provider’s actual staffing, language proficiency, access controls, training, and service performance rather than assuming geography establishes quality.
How long does a financial services BPO pilot take to launch?
Timing depends on scope, system permissions, contractual and security reviews, training, and any specialized requirements. Set readiness gates before committing to a date. Begin with a limited workflow and expand after documented acceptance criteria are met.
Bilingual Nearshore Support in Mexico
Build a More Accountable Financial Support Program
Bring your support volumes, English-Spanish coverage needs, workflow boundaries, and security questions to CallZent. Discuss a nearshore program with defined responsibilities, reporting, and pilot goals.